Who Is NMI?
The payments technology behind a local business relationship—and the questions Augusta owners should ask before choosing a setup.
Prepared October 13, 2026 · Vibe Coding of Augusta
Optional local synthetic narration · A spoken overview, with its exact transcript below.
Download MP3Read the exact spoken transcript
Who is N M I? The payments technology behind a local business relationship.
When a customer taps a card, pays on your website, or settles a bill from a phone, you see a simple result. Approved, or declined. Behind that moment sits a chain of businesses and technology. Knowing who does what helps you ask better questions before you sign up, and find the right help afterward.
N M I is one of the companies behind that chain. It provides payments technology through partners, often working in the background while another business handles the relationship with the merchant. You may never have noticed its name, even if you have encountered technology it supports.
This is a spoken overview of our company profile. For an Augusta business owner, the useful question is whether the technology, account terms, equipment, and human guidance fit how your business gets paid.
N M I describes itself as a payment acceptance platform built around partners. Its platform includes a payment gateway, merchant relationship software, and payment processing services. A gateway carries payment information between your checkout and the other participants needed to authorize a transaction.
The gateway is part of a larger arrangement. N M I distinguishes its gateway software from N M I Payments, its acquiring solution. Some partners use the gateway with a separate processor relationship. Others use a more integrated arrangement. Ask who holds your merchant account, who handles funding, and which agreement establishes the terms.
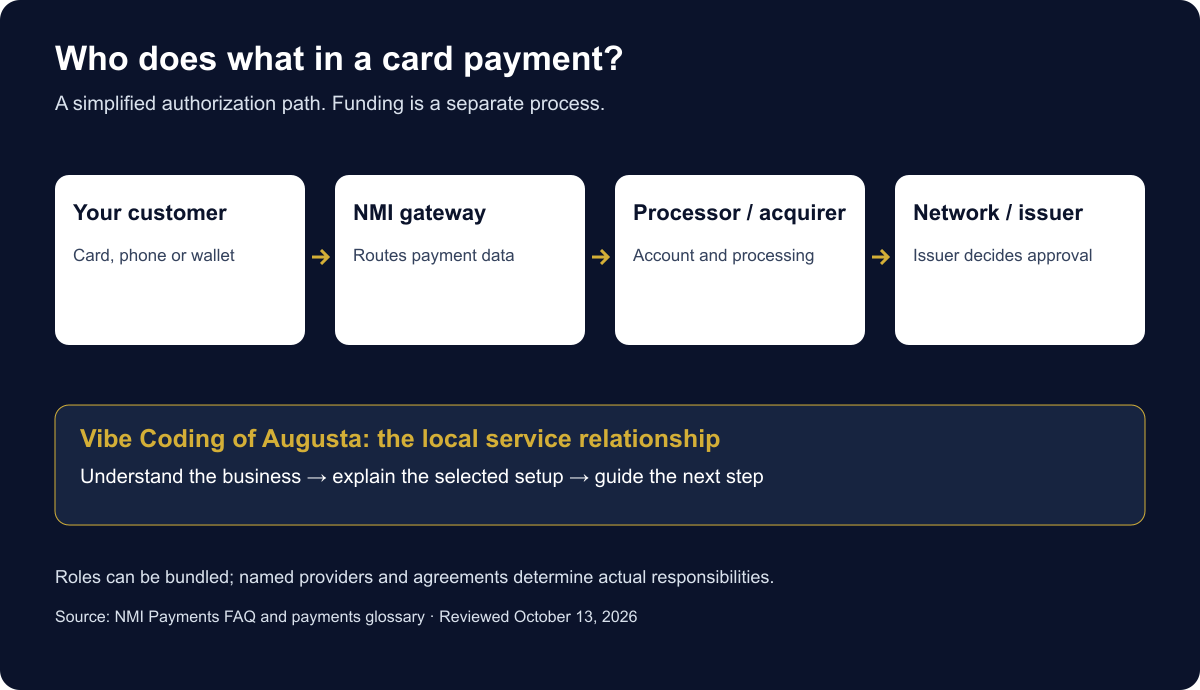
Think of the checkout as the front door. The gateway helps your transaction reach the systems that can act on it. The processor and acquiring relationship handle other parts of processing and funding. The customer’s card issuer makes the authorization decision. Your local service provider helps you understand and use the setup you have selected.
Before you commit, ask who handles a setup problem, a disputed transaction, or a delayed deposit. A clear answer is more useful than a promise that one app does everything.
N M I says it was founded in two thousand one to serve organizations in the payments industry. Its company milestone article describes reaching its ten billionth transaction. That is a cumulative historical milestone, not an annual count.
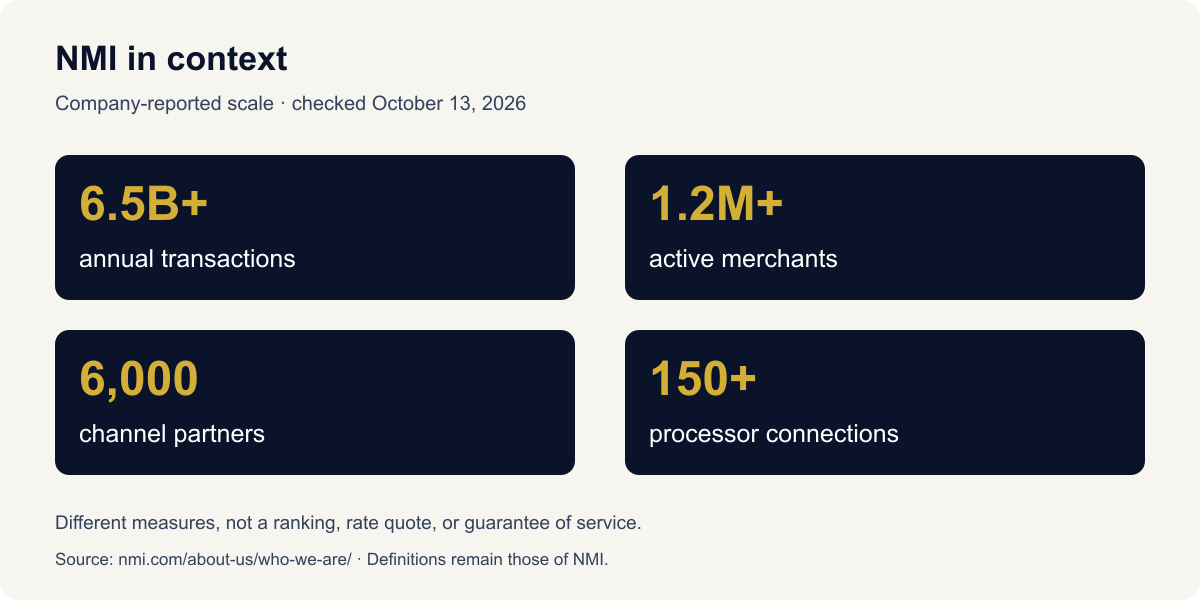
On the company page checked October thirteenth, twenty twenty-six, N M I reports more than six point five billion annual transactions, more than one point two million active merchants, six thousand channel partners, and more than one hundred fifty processor connections.
These are the company’s own figures. They describe the breadth of its infrastructure and partner network. They are not an independent audit or a market ranking. They do not establish your approval, your rate, or a guaranteed service outcome.
Why does N M I work through partners? Its model allows banks, payments organizations, and software providers to use its infrastructure when serving businesses. Those organizations have different roles and responsibilities. A partner does not automatically have the authority of a bank.
N M I also supports arrangements where a partner presents supported services under its own brand. That means a familiar local business name can sit over technology supplied by another company. Ask which companies appear in your agreements, who bills each fee, and where you get support.
For a small business, the range of technology is useful only when it answers a practical need. Collect payment at the counter. Collect it after a service visit. Or accept it through a website. Supported mobile and integration options exist, but your device, application, account, and configuration still determine what you can use.
A service business might ask whether its exact phone supports the selected payment method. A shop might ask whether its existing checkout equipment can stay. A business selling online and in person might ask how it will review both types of transactions. These are example questions, not promises about a particular package.
Where does Vibe Coding of Augusta fit? Its approved business approach is practical, plain-language guidance with people responsible for important decisions. Understand the customer first. Explain the available path. Recommend a reasonable fit.
Current Founder-confirmed records say Eric can assist with manual N M I merchant onboarding. A merchant’s approval and working setup remain separate outcomes. Assisted onboarding also differs from an automated website application flow.
Our editorial assessment is that N M I’s partner model can support this local approach. The technology platform supplies infrastructure. The local business helps an owner understand the arrangement and the next step. Eric Lamar Roane explains his choice this way. I chose N M I because I saw a company committed to standing behind merchants, investing in current payment technology, and supporting its affiliates and the merchants those affiliates bring on board. That commitment matters to me when choosing a partner for the businesses I serve.
If your current payment arrangement works, switching just because another platform has more features may create unnecessary work. Begin with a real problem. Can customers pay where you finish the job? Does your online checkout work with the way you track sales? Do you understand your statement?
Then compare the complete written arrangement. Processing charges, gateway charges, equipment, setup assistance, ongoing service, and any commitments or exit terms. Platform size alone does not establish a lower price. Every feature is not automatically included.
Account approval, payment acceptance, and money reaching your bank are different milestones. Ask how each will be verified for your account.
You do not need to become a payments engineer to make an informed choice. You do need to know the companies involved, the costs you are agreeing to, the tools that will work for you, and the person who will help.
Contact Vibe Coding of Augusta. Tell us where you take payments now, what equipment or phone you use, and what you would like to improve. Begin with business needs and ordinary contact details. Sensitive application information belongs in the appropriate secure provider process.
A practical company profile for Augusta and CSRA business owners. Prepared October 13, 2026.
When a customer taps a card, pays on your website, or settles a bill from their phone, you see a simple result: approved or declined. Behind that moment sits a chain of businesses and technology. Knowing who does what helps you ask better questions before you sign up—and find the right help afterward.
NMI is one of the companies behind that chain. It provides payments technology through partners, often working in the background while another business handles the relationship with the merchant. You may never have noticed its name even if you have encountered technology it supports.
For a local owner, the useful question is not simply whether NMI is a large company. It is whether the combination of technology, account terms, equipment, and human guidance fits how your business gets paid.
What kind of company is NMI?
NMI describes itself as a payment acceptance platform built around partners. Its platform includes a payment gateway, merchant relationship software, and payment processing services. A gateway is the connection that carries payment information between your checkout and the other participants needed to authorize the transaction. Source: NMI company profile.
The gateway is part of a larger arrangement. NMI’s own FAQ distinguishes its gateway software from NMI Payments, its acquiring solution. Some partners use the gateway with a separate processor relationship; others use a more integrated arrangement. That distinction matters when you ask who holds your merchant account, who handles funding, and which agreement establishes the terms. Source: NMI payment FAQ.
Think of the checkout as the front door. The gateway helps your transaction reach the people and systems that can act on it. The processor and acquiring relationship handle other parts of processing and funding. The customer’s card issuer makes the authorization decision. Your local service provider helps you understand and use the particular setup you have selected. Source: NMI payments glossary.
Those responsibilities should be explained before you commit. A helpful question is: “If I have a setup problem, a disputed transaction, or a delayed deposit, who handles each one?” A clear answer is more useful than a promise that one app does everything.
A company with a history beyond today’s payment apps
In its company milestone article, NMI says it was founded in 2001 to serve organizations operating in the payments industry. The company also describes reaching its ten-billionth transaction as a cumulative milestone. That is a historical total, not an annual transaction count. Source: NMI’s company-history and transaction milestone.
That origin helps explain its business model today: NMI supplies infrastructure that other companies use to serve merchants. Its name does not have to be prominent on every checkout for its technology to have a substantial role.
The practical value of a company’s history is context. It gives you something more substantial to examine than an unfamiliar app name. It does not, by itself, establish how well your account will be supported, whether your application will be approved, or what your particular arrangement will cost.
How large is NMI—and what do those figures mean?
On its company page checked October 13, 2026, NMI reports:
| Measure | NMI’s reported figure | How to read it |
|---|---|---|
| Annual transactions | 6.5 billion+ | A count of transactions, not dollars |
| Active merchants | 1.2 million+ | Merchants served across its ecosystem, not VCA customers |
| Channel partners | 6,000 | Organizations through which its technology reaches businesses |
| Processor connections | 150+ | Platform connections, not a promise every merchant can use every processor |
These are NMI’s self-reported figures, not an independent audit or a market-share ranking. They indicate the breadth of the infrastructure and partner network. They do not prove guaranteed uptime, universally lower rates, or a particular service outcome. Source: NMI company profile.
For an Augusta owner, the better follow-up is specific: which connection will my account use, what does that arrangement support, and who takes responsibility when I need help?
Why NMI works through partners
NMI describes a model in which banks, independent sales organizations, payment facilitators, and software providers deliver services using its infrastructure. These organizations have different roles; being a partner does not make each one a bank or give each one the same authority. Source: NMI reseller-model guide.
This model separates the technology platform from the person or business serving the merchant. A partner can work with an owner’s actual needs—how the business collects payment, which systems it uses, and what assistance it needs—while using infrastructure provided further up the payments chain.
NMI also supports white-label arrangements, where a partner presents supported services under its own brand. The exact branding depends on configuration. A familiar local name on the front of a service can therefore sit over technology supplied by another company. Source: NMI payment FAQ.
That arrangement can be useful, but clarity still matters. Ask to see the names and responsibilities of the companies in your agreements. Know which organization bills each fee and where to get support. A local relationship should help make the arrangement easier to understand.
What its range can mean for a small business
An owner should be able to start with a practical need: collect payment at the counter, after a service visit, or through a website. NMI’s mobile offering includes phone-based acceptance, mobile readers, and developer tools for supported applications. Device, app, account, and configuration requirements still determine what a particular business can use. Source: NMI mobile payments.
Its broader approach also includes connections across different processors and hardware. NMI describes this flexibility as a way for software businesses to support more than one technical arrangement. That is a platform characteristic; it does not mean switching providers is automatic, free, or suitable for every account. Source: NMI on processor and hardware flexibility.
Here is how to turn that breadth into a sensible conversation:
- A service business: “Can I collect payment at the job using the exact phone and app I have?”
- A shop: “Can this work with my current checkout equipment, or would replacement be necessary?”
- A business selling online and in person: “How will I review both types of transactions, and which parts of my current system can stay?”
These are example questions, not claims about a current VCA package. The best setup is the one you can use consistently. A long feature list has little value if a feature is unavailable on your account or adds complexity you do not need.
Where Vibe Coding of Augusta fits
Vibe Coding of Augusta’s approved business approach is practical, plain-language guidance with human responsibility. Its role is to understand the customer first, explain the available path, and recommend a reasonable fit. That approach belongs in a payment conversation just as much as it does in a website or AI project.
Current Founder-confirmed operating records say Eric can assist with manual NMI merchant onboarding. A particular merchant’s approval and working setup remain separate outcomes. Manual assisted onboarding also should not be confused with the readiness of an automated website application flow.
The useful pairing is straightforward: a payments technology platform supplies infrastructure, while a local business helps an owner understand the chosen arrangement and the next step. Our editorial assessment is that NMI’s partner model can support that approach. It leaves room for a local service relationship while offering technology that can be evaluated against the merchant’s requirements.
Why I chose NMI — a note from Eric
I chose NMI because I saw a company committed to standing behind merchants, investing in current payment technology, and supporting its affiliates and the merchants those affiliates bring on board. That commitment matters to me when choosing a partner for the businesses I serve.
Eric Lamar Roane, Founder, Vibe Coding of Augusta. This is my personal reason for selecting NMI; the services and terms available to each merchant still depend on the approved setup.
When changing systems may not be worthwhile
If your existing arrangement works, your statements are understandable, and you receive adequate help, switching simply because another platform has more features may create unnecessary work.
Start by identifying a real problem. Are customers unable to pay where you finish the work? Is your online checkout disconnected from the way you track sales? Are you unsure which charges appear on your statement? Write down the problem before shopping for a solution.
Then compare the full arrangement: processing charges, gateway charges, equipment, setup assistance, ongoing service, and any commitments or exit terms. Your written proposal and agreements should establish the applicable costs and conditions. A company profile cannot substitute for that review.
The same discipline applies to expectations. Account approval, payment acceptance, and money arriving in your bank are different milestones. Ask how each one will be verified for your account rather than treating a completed form as a finished setup.
Questions owners often ask
Is NMI the same company as Vibe Coding of Augusta?
No. NMI is the payments technology company discussed here. Vibe Coding of Augusta is Eric Lamar Roane’s local business. The provider and service responsibilities depend on the arrangement and agreements selected for the merchant.
Is NMI a bank?
Its platform should not be confused with the bank that issues your customer’s card or the acquiring arrangement that supports your merchant account. Ask which named organizations perform those roles in your account documents. Source: NMI payments glossary.
Does NMI’s size mean I will pay less?
No. Platform scale does not establish your merchant’s price. Compare a complete written proposal with your current statement, including separate service and gateway costs where applicable.
Will every NMI feature be included?
No. Platform capabilities and your enabled services are different things. Confirm the named feature, compatible device or integration, applicable charge, and availability for your account before relying on it.
Do I have to replace everything to explore it?
Exploration should begin with what you already have. NMI’s gateway can work with supported processor relationships, but compatibility and any contractual changes must be checked for your specific setup. Source: NMI payment FAQ.
Start with how your business gets paid
You do not need to become a payments engineer to make an informed choice. You do need to know the companies involved, the costs you are agreeing to, the tools that will work for you, and the person who will help you take the next step.
Tell Vibe Coding of Augusta where you take payments now, what equipment or phone you use, and what you would like to improve. Start with business needs and ordinary contact details; provide sensitive application information only through the appropriate secure provider process.
Contact Vibe Coding of Augusta to discuss whether a supported payment setup fits your business.


0 Comments