When card fees rise, some owners look at passing part of the cost to customers. There are two common approaches, and they are not the same thing. This post explains the basics. It is not legal advice, and the rules need to be confirmed before you change how you charge.
Cash discount vs. surcharge
A cash discount means your posted price is the card price, and customers who pay cash or check get a discount. A surcharge means you add a fee to a credit card sale at checkout. A third approach, dual pricing, shows two prices for each item, one for cash and one for card.
Rules to confirm before you start
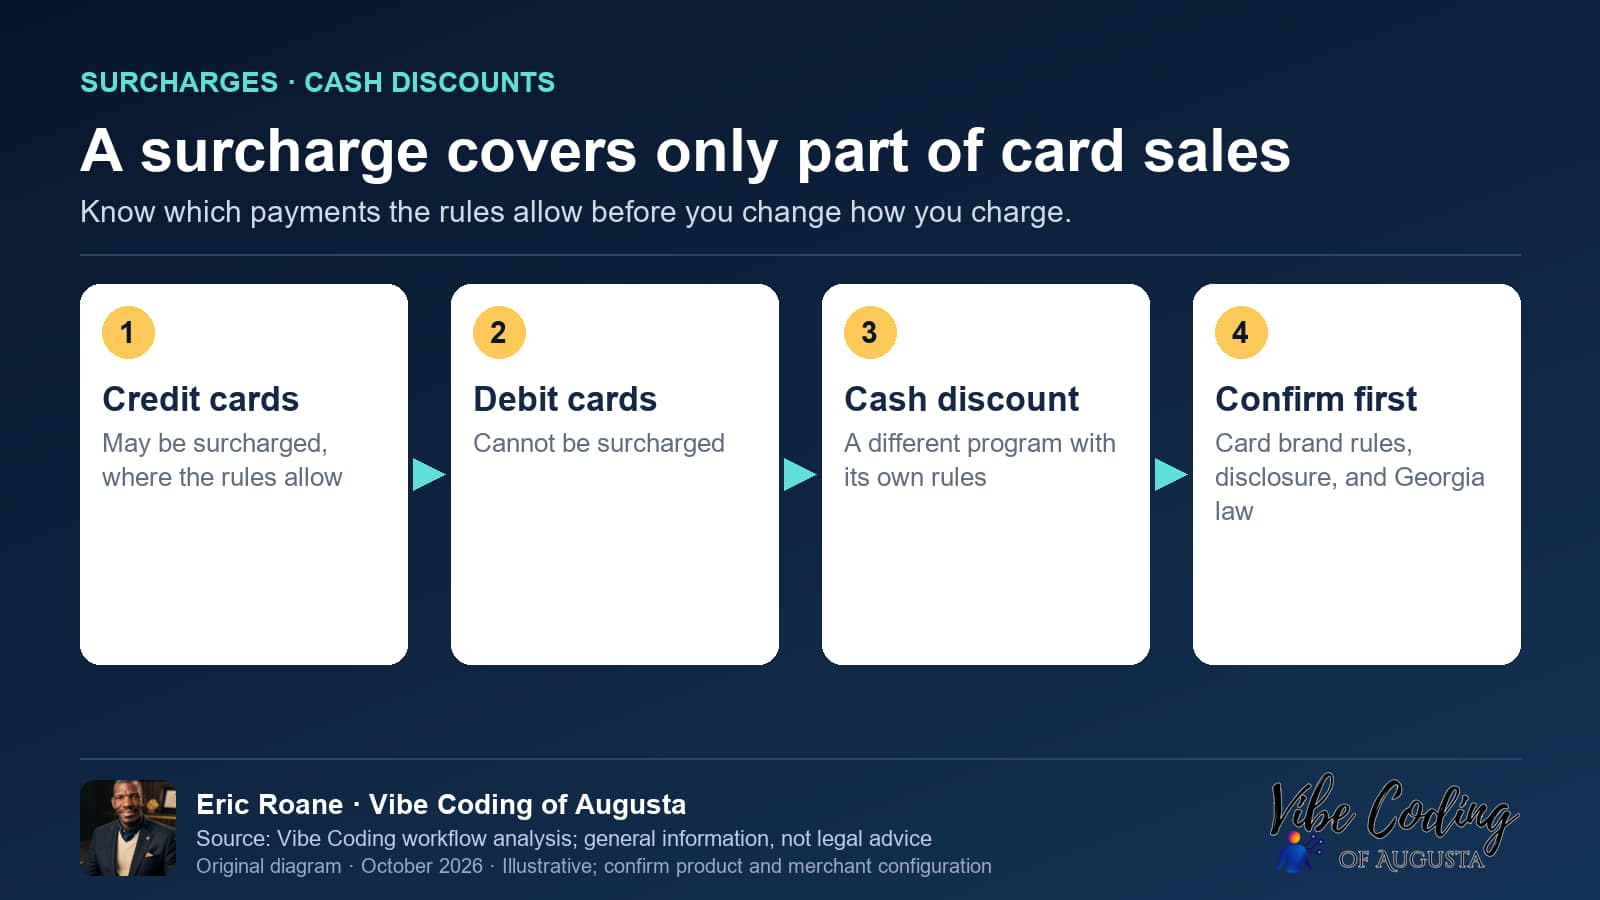
- Card brand rules. Visa and Mastercard publish their own surcharge rules, including a cap on the surcharge amount, notice to the brands and your processor before you begin, and required disclosure to customers. The cap and notice period can change, so check the current rules.
- Debit cards. Card brand rules do not allow a surcharge on debit card transactions. Your system needs to tell debit from credit correctly.
- Disclosure. Customers should see the policy before they pay, and the charge should appear as its own line on the receipt.
- State and local law. Confirm current Georgia requirements and any rules that apply to your type of business with an attorney or your processor.
- Your processing agreement. Your provider must support the program and may have its own requirements.
Why a surcharge only covers part of your card sales
Example: $10,000 in monthly card sales, $7,000 on credit cards and $3,000 on debit cards.
Illustrative split only. A surcharge also cannot be more than the rules allow, so it covers some of the cost, not all of it.
Will it save money?
It may reduce what you absorb in card fees, but it can also change how customers feel about paying. Savings depend on how many customers pay by card, the mix of debit and credit, and whether customers shift to cash. We cannot promise a number, and you should be wary of anyone who does.
General information only, not legal advice. Rules change; confirm current card brand and Georgia requirements before offering a surcharge or cash discount.
Ready to look at a merchant account for your business? Start with a short form, and we will walk you through the next steps.


